Client Login


Global markets continue to balance resilient economic activity against persistent inflation and a more uncertain outlook for monetary policy. Last week brought significant fiscal and central-bank developments, while attention this week turns to the Bank of England and further evidence on the health of the US economy.
Last week
• UK fiscal policy: The Budget and its implications for government borrowing and gilt issuance were a key focus for UK markets.
• Central banks: Both the Federal Reserve and European Central Bank announced their latest monetary policy decisions with rates unchanged and inflation remaining central to the outlook.
• Equities: Corporate earnings continued to drive individual market moves, with technology and AI-related investment attracting particular scrutiny, including earnings updates from SK Hynix, Microsoft, Alphabet and Amazon.
• Fixed income: Government bond markets remained sensitive to changing expectations for inflation, growth and the future path of interest rates.
• Geopolitics: Developments in the Middle East continued to influence energy markets and the broader inflation outlook.
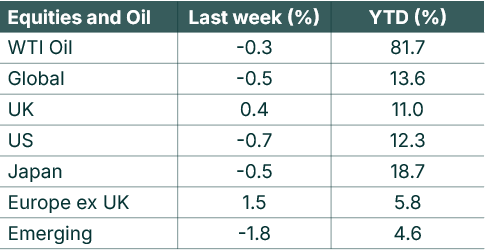
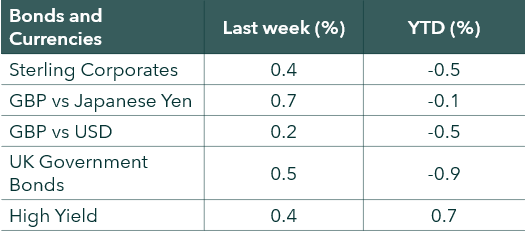
Source: Bloomberg. Currency GBP.
This week
It will be a particularly busy week for corporate earnings, with focus also being given to US mid-term elections, the Bank of England MPC meeting, and the usual flow of monthly macroeconomic data.
• Bank of England: Thursday’s monetary policy decision will be the principal domestic event for UK investors.
• US politics: The midterm elections will be closely monitored for their implications for the US policy outlook.
• Corporate earnings: Results from major companies will continue to test current equity-market valuations and earnings expectations. We will see over 1,000 earnings updates including Apple, Palantir and McDonalds.
• US economic data: Labour-market and activity data will provide further evidence on the strength of the US economy. This will include services and manufacturing PMIs, non-farm payrolls, US job openings and unemployment data and Michigan Consumer Sentiment data.
More details
UK outlook: The UK fiscal position returned to the forefront last week, with investors assessing the implications of the Budget for government borrowing, gilt issuance and the wider economic outlook. Attention now turns to Thursday’s Bank of England decision, where policymakers continue to balance inflationary pressures against the outlook for economic activity. The accompanying guidance could prove as significant as the decision itself, with expectations for the future path of Bank Rate remaining an important influence on gilt yields, sterling and UK equity valuations.
US economy and interest rates: In the US, investors continue to assess the resilience of the economy alongside the persistence of inflation and the implications for monetary policy. This week’s labour-market and activity data will therefore be closely watched for evidence of whether economic momentum is moderating and what that could mean for the future path of interest rates, while the US midterm elections provide an additional political consideration for markets as investors assess the potential implications for fiscal and economic policy.
Equity markets: Corporate earnings remain an important test for equity markets, particularly following strong performance and elevated valuations across parts of the technology sector. Artificial intelligence remains a major area of investment, but the scale of associated capital expenditure has increased scrutiny on the returns companies are generating from that spending. Earnings growth, margins and forward guidance are therefore likely to remain key differentiators, particularly where valuations leave relatively little room for disappointment.
Investment outlook: The macroeconomic environment remains finely balanced, with resilient economic activity set against persistent inflation and uncertainty over the future path of monetary policy. For investors, the focus is increasingly on how long policy may need to remain restrictive, rather than simply the timing of the next change in interest rates. Against this backdrop, diversification across asset classes, regions and investment styles remains important, with this week’s Bank of England decision and US economic data providing further evidence on the direction of policy into the closing months of the year.
The value of investments and the income from them can go down as well as up and you could get back less than you invested. Past performance is not a reliable indicator of future performance.
The content of this article is not intended to be or does not constitute investment research as defined by the Financial Conduct Authority. The content should also not be relied upon when making investment decisions, and at no point should the information be treated as specific advice. The article has no regard for the specific investment objectives, financial situation or needs of any specific client, person, or entity.